RMSE in Bayesian Context
- 主要言語
- Python
- スター
- 20.4k
- フォーク
- 4.6k
- 平均マージ
- 19時間 52分
- マージ済み PR(30日)
- 1
説明
When accessing model fit, it seems like a lot of people have been using existing packages in R or Python.
However, with a package, we are simply getting the traditional RMSE as:
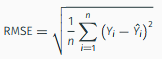
In the Bayesian context where we have posterior samples from each prediction of interest, we can express this equation as:
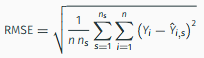
I know there's now a `m.predictive_samples(future)` function built into v0.2 so this wouldn't be hard to add. What are people thoughts? It seems like we are losing a lot of the uncertainty we gain from fitting a Bayesian model by simply using the posterior mean for model fit evaluation.
コントリビューションガイド
評価
この issue はまだ評価されていません。